 tolapay
Selling software into Nepal from abroad: the 13% VAT and 2% Digital Service Tax
The two regimes the Inland Revenue Department applies to non-resident digital services, the NPR 3 million threshold, and why billing from a Nepali entity changes the picture.
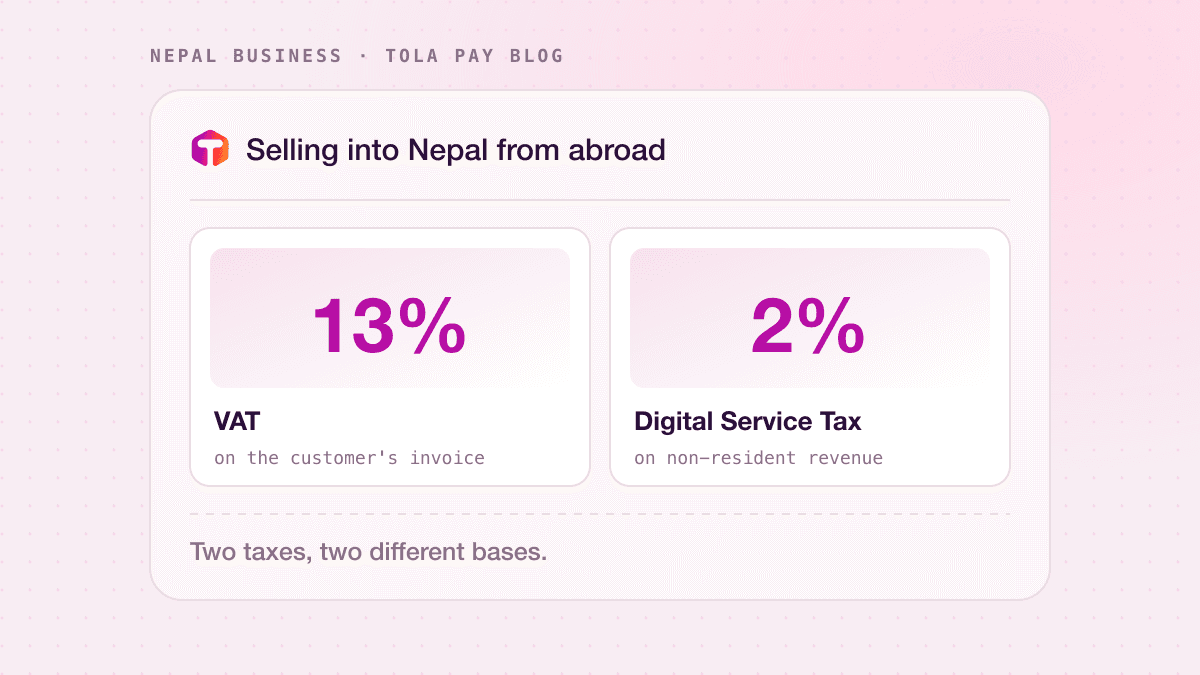
If you sell SaaS to Nepali consumers from outside Nepal, the IRD has had you in scope since 2022. Two separate obligations apply, and founders routinely confuse them.
13% VAT on B2C digital services
Under the IRD's procedure for VAT on digital services by non-residents, a foreign supplier whose Nepal consumer sales exceed NPR 3 million in the previous 12 months (raised from NPR 2 million in the August 2025 update) must register, collect 13% VAT from consumers and file monthly by the 25th. B2B supplies are handled by the Nepali buyer under reverse-charge rules rather than by the foreign seller.
2% Digital Service Tax
Separately, the Digital Service Tax Act 2024 levies a 2% direct tax on the non-resident supplier's covered transaction value (excluding VAT), with a NPR 3 million annual exemption, annual filing, a 0.1% fine per year for a missed return and 15% interest on late payment.
Why this matters to Nepali founders
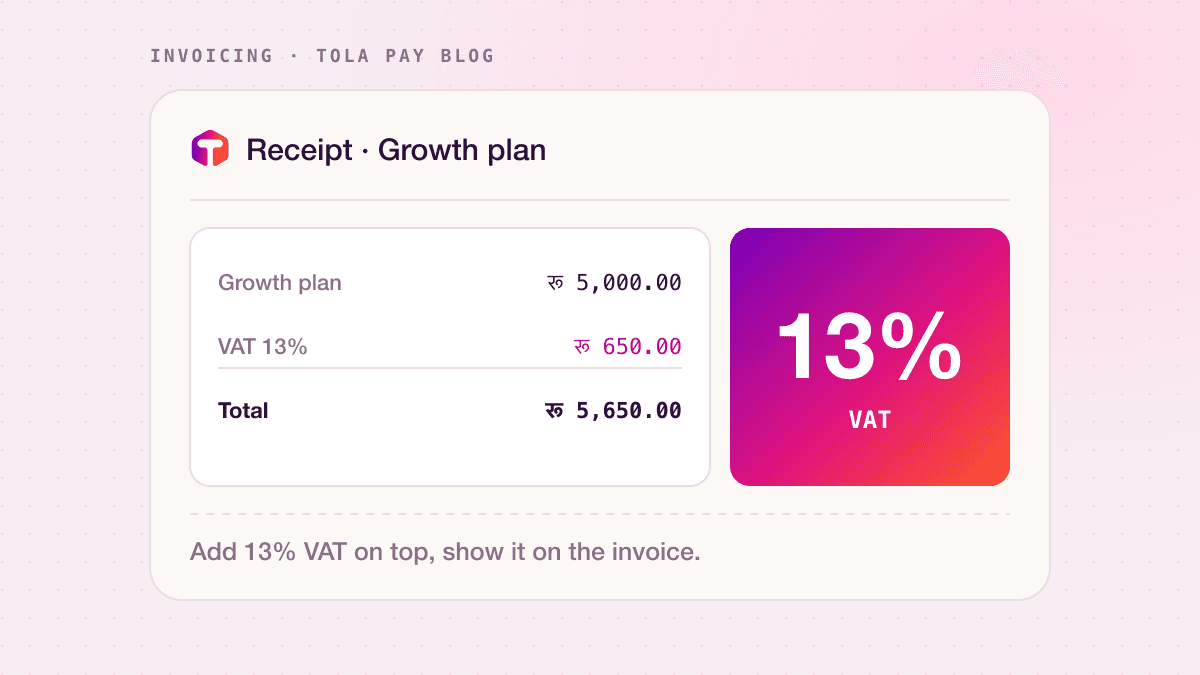
If you are incorporated in Nepal and bill in NPR, you are simply a VAT-registered domestic seller: 13% on the invoice, monthly returns, no DST. Routing revenue through a foreign entity to use a foreign billing tool can quietly turn you into a non-resident digital supplier to your own market. Keep the billing where the company is.
What Tola Pay does and doesn't do
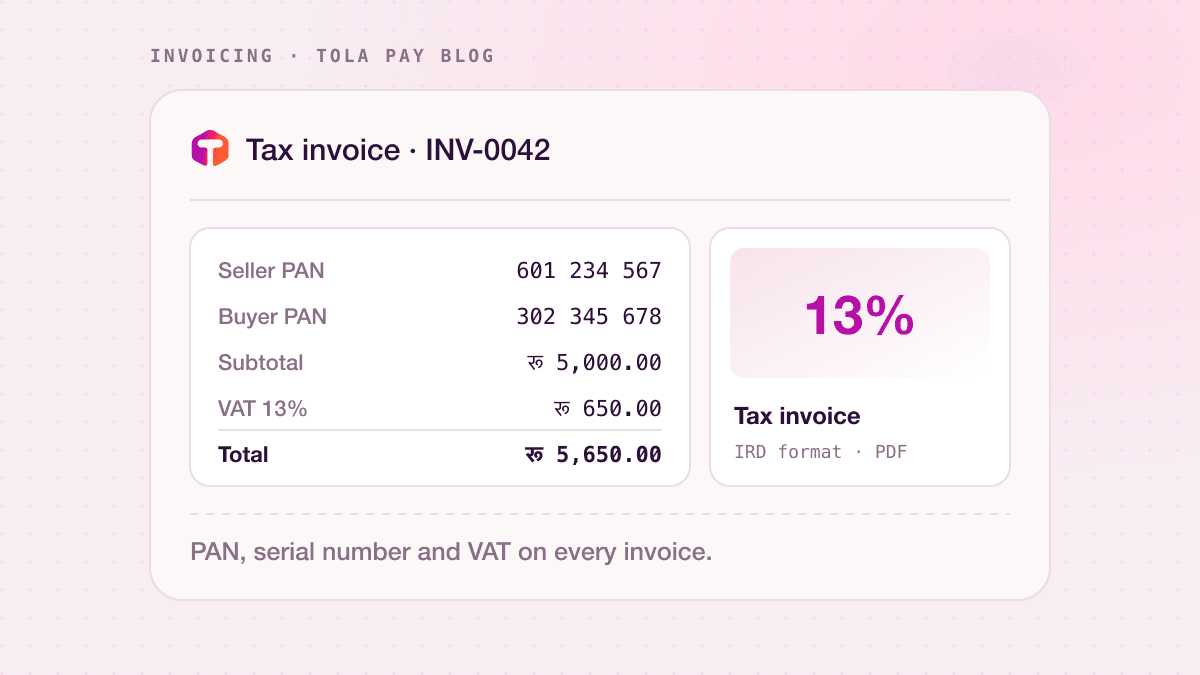
Tola Pay issues compliant NPR invoices with the VAT split for Nepali businesses. It is not a merchant of record and does not register for VAT or DST on your behalf; your accountant owns the filings. We just make the numbers come out of one ledger.
 Invoicing · 21 Oct 2026
 Invoicing · 25 Sept 2026
 Payments · 28 Oct 2026